
It is a loan, not a lease
With a GoodLeap solar loan, you own the panels and owe GoodLeap the balance. GoodLeap services its own loans, so its statement and app are where payoff and account questions start. GoodLeap also offers leases and PPAs. If you have one of those, see the solar lease exit guide or the solar PPA exit guide instead.
Getting out of a loan usually means one of four things: canceling right after signing, paying it off, refinancing it, or raising a claim because the sale was misrepresented. Your own loan agreement controls, so keep it in front of you.
Canceling right after signing
The installation contract. If you signed at home, the FTC’s Cooling-Off Rule generally gives you until midnight of the third business day after the sale to cancel for a full refund. Many states add longer windows for solar or home solicitation sales. Check our state solar laws page. Send the cancellation to the installer in writing, postmarked by the deadline, and send a copy to GoodLeap so it knows not to fund the project. Our cancellation letter can help.
The federal 3-day right to rescind. The Truth in Lending Act gives a separate right to cancel a credit transaction that takes a security interest in your principal home. It runs until midnight of the third business day after the latest of signing, receiving the rescission notice, or receiving the required disclosures. If those were never given, it can last up to three years.
This right may not reach a typical GoodLeap solar loan. GoodLeap says its loans are secured by a lien on the solar equipment, recorded as a UCC-1 and county fixture filing, and that the filing is not a lien on your home. A federal appeals court held in 2015, in a case about water treatment equipment, that a fixture filing limited to the equipment did not trigger this right. Check whether your loan papers include a Notice of Right to Cancel. If they do, or if your loan was secured by your home, ask a consumer attorney promptly.
Were you misled about your solar?
Tell us what happened. It takes about two minutes, and you decide what happens next.
See my optionsPayoff, refinancing, or selling your home
- Payoff. In the GoodLeap Home app, choose the account and tap Payoff Quote for a breakdown. GoodLeap says it never charges a fee or penalty for prepayments.
- Refinancing. A credit union, bank, or mortgage refinance can replace the loan. Compare total cost, not just the monthly payment. GoodLeap says it may lift its county UCC-1 filing for a limited time during a refinance if it can refile at closing.
- Selling your home. Most sellers pay off the balance from the sale. A buyer can apply to take over the loan, but GoodLeap must approve it. If the assumption is not approved, the loan must be paid off at the sale. GoodLeap lists 1-800-345-9372 for home sale questions.
When the loan is paid, ask GoodLeap to terminate its UCC-1 filing and confirm it was recorded. GoodLeap directs filing questions to filings@goodleapsupport.com.
The 18-month paydown and payment reset
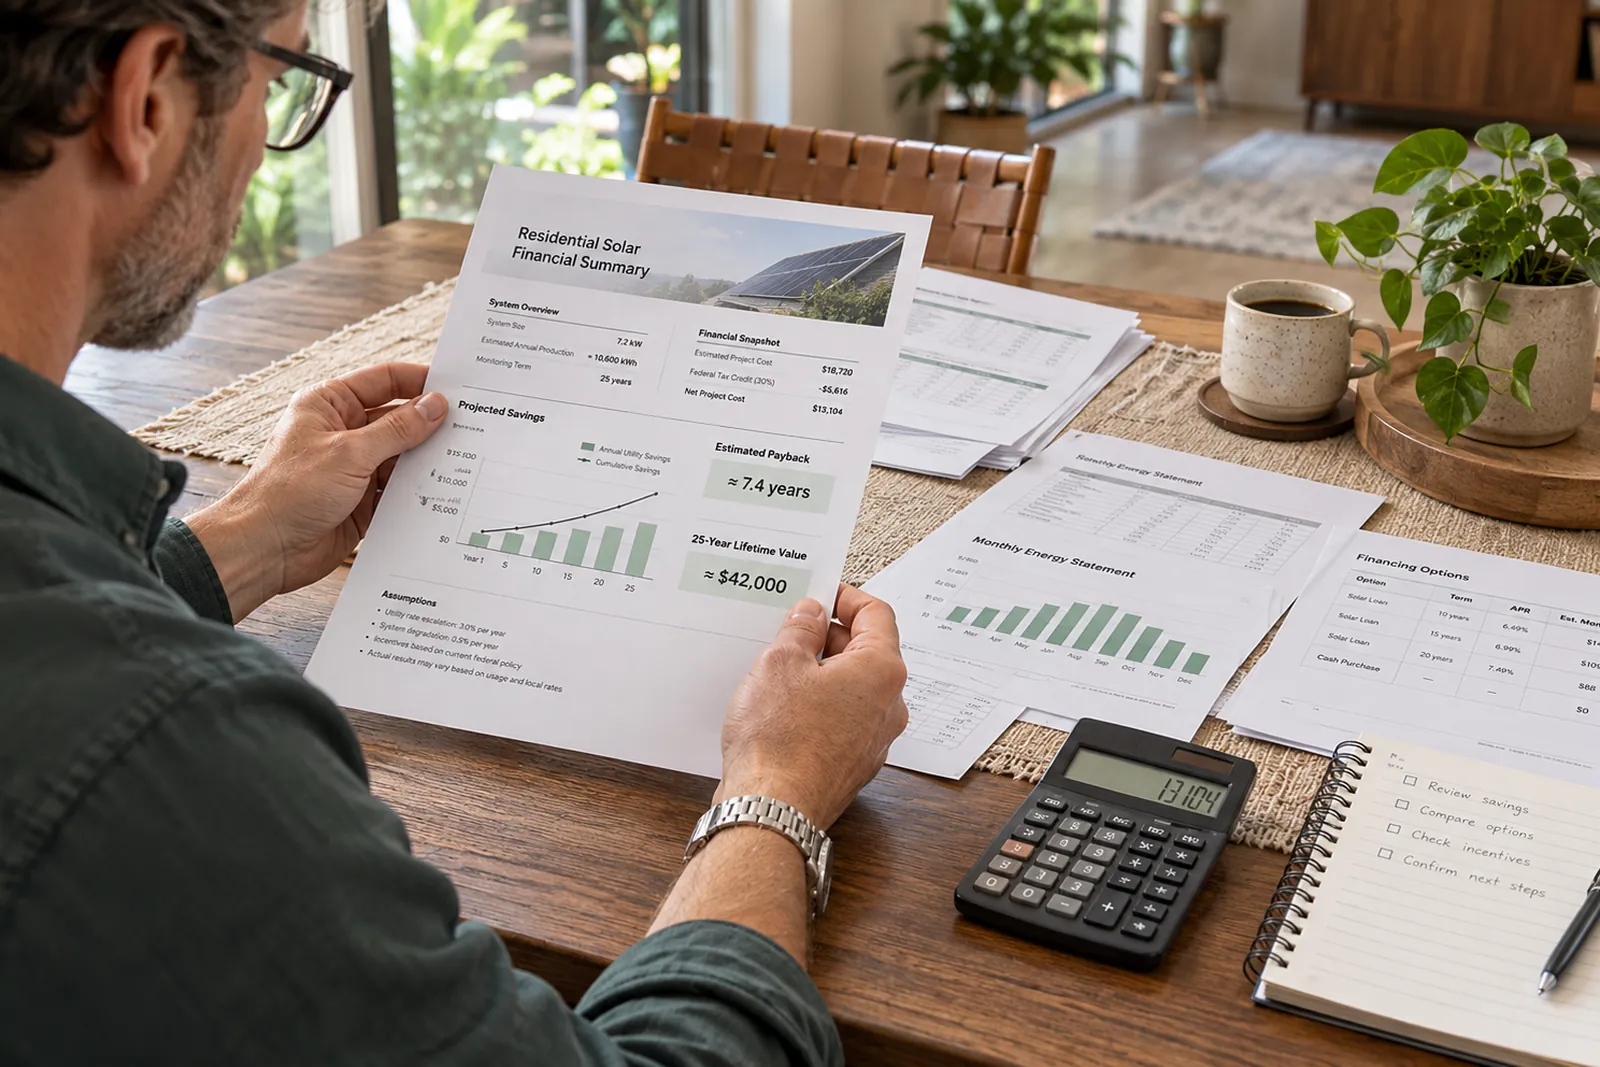
GoodLeap says many of its loans have lower payments for the first 18 months, giving time to apply a tax credit or make extra payments. After month 18, the loan re-amortizes, and the payment adjusts based on how much you paid down. A smaller paydown can mean a higher payment.
The CFPB reported in 2024 that many solar loans expect a prepayment of about 30 percent of the principal, matching the federal tax credit, and reset to a higher payment in the 19th month if it is not made. If you were told the tax credit would cover this and it did not, keep that paperwork. If the new payment is not affordable, contact GoodLeap early. Its FAQ lists 1-844-562-6725 for hardship help.
Dealer fees and the Minnesota lawsuit
A low advertised rate can come with a large fee built into the loan balance. The CFPB reported that these fees typically run 10 to 30 percent of the cash price and can exceed 50 percent. Compare your loan amount to the system’s cash price with our dealer fee calculator, and read how dealer fees hide a markup.
In March 2024, the Minnesota Attorney General sued GoodLeap, Sunlight Financial, Solar Mosaic, and Dividend Solar Finance. The state alleges the lenders advertised low rates while concealing upfront fees that raised most borrowers’ costs by 15 to 30 percent, and collected about $35 million from Minnesota consumers since 2017. These are allegations. The case has not been decided, and it does not change any borrower’s payments.
If the installer misrepresented the deal
Solar loans like GoodLeap’s are often arranged by the installer at the kitchen table. That matters because of the FTC Holder Rule. When a seller arranges the financing, the rule requires the credit contract to include a notice saying that any holder is subject to the claims and defenses the borrower could raise against the seller. Your recovery under that notice is generally limited to what you have paid on the loan.
Look for a paragraph in your loan agreement that begins with the word NOTICE and mentions claims and defenses against the seller. Whether it is there, and how far it reaches, depends on your documents and your state’s law, so have an attorney review it. Read misled by a solar salesperson and tell us what happened.
Disputes and complaints
Start with GoodLeap’s compliance office: consumercomplaints@goodleap.com, 916-475-1255, or 8781 Sierra College Blvd., Roseville, CA 95661. Put the dispute in writing, include your account number, and keep copies. Our complaint letter template can help.
If that does not resolve it, file with the CFPB, your state attorney general, and your state’s financial regulator. Keep paying while a dispute is open unless an attorney advises otherwise. See our complaint guide.
Common questions
Can I cancel my GoodLeap solar loan?
Sometimes, if you act quickly. A cooling-off window may let you cancel the installation contract within days of signing. The federal 3-day right to rescind applies only to loans secured by your home, which may not include a typical GoodLeap solar loan.
Does GoodLeap charge a prepayment penalty?
GoodLeap says it never charges a fee or penalty for prepayments. You can get a payoff quote in the GoodLeap Home app.
Why did my GoodLeap payment go up?
Many GoodLeap loans re-amortize after month 18 based on how much you paid down. If you did not make the expected paydown, the payment can rise.
Is the GoodLeap UCC filing a lien on my house?
GoodLeap says its UCC-1 fixture filing covers the solar equipment only and is not a lien on your home. It still usually needs to be paid off or released when you sell or refinance.
Can I refinance a GoodLeap solar loan?
Yes. A bank, credit union, or mortgage refinance can pay it off, and GoodLeap does not charge a prepayment penalty. Compare total cost before you switch.
Sources
- GoodLeap: Frequently asked questions. Payoff quotes, no prepayment fee, 18-month re-amortization, UCC-1 filing, home sale, hardship
- GoodLeap: Contact us. Account support and complaints contacts
- 12 CFR 1026.23: Right of rescission (CFPB). Three-day right to cancel home-secured credit
- FDIC: FTC Rule on Preservation of Claims and Defenses (Holder Rule). Notice requirement and recovery limit
- Minnesota Attorney General: lawsuit against solar lenders (March 8, 2024). Dealer fee allegations against GoodLeap and others
- CFPB: Issue Spotlight, Solar Financing (August 2024). Prepayment expectations, 19th-month reset, and fee ranges
- National Law Review: 11th Circuit opinion on fixture filings and TILA. Lankhorst v. Independent Savings Plan Co. (2015)
General information, not legal advice.
This guide can’t tell you whether a right applies to your agreement. For that, talk with a licensed attorney in your state.